Buy consulting24.eu ?
We are moving the project
consulting24.eu .
Are you interested in purchasing the domain
consulting24.eu ?
domain@kv-gmbh.de · 0541-91531010
Buy consulting24.eu ?
What is a primary mortgage financing?
A primary mortgage financing refers to the initial loan that a borrower obtains from a lender to purchase a home or property. This type of financing is typically used to cover the majority of the purchase price of the property, and is secured by the property itself. The borrower makes regular payments to the lender over a set period of time, usually 15 or 30 years, until the loan is fully repaid. Primary mortgage financing is a common way for individuals to become homeowners without having to pay the full purchase price upfront. **
Where can I get a mortgage deed?
You can obtain a mortgage deed from a mortgage lender or financial institution that is providing you with the loan for purchasing a property. The mortgage deed is a legal document that outlines the terms and conditions of the mortgage agreement between the borrower and the lender. It is typically prepared by the lender's legal team and signed by both parties before the loan is disbursed. **

Similar search terms for Mortgage
Top-Angebote
Products related to Mortgage:
-
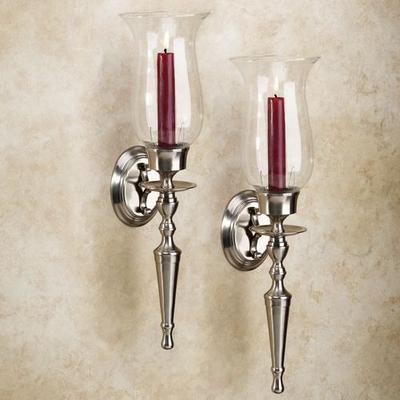
Flythe Consulting Arika Wall Sconce Pair, Pair, Satin NickelThe Arika Wall Sconce Pair is an adaptation of old-fashioned light fixtures, with an appealing design that will complement modern decor. The lacquered solid brass sconces have 4.75 dia.x7 H clear glass hurricanes that will protect your standard...179,00 $*Shipping: 22,95 $Secure redirect to the provider
-
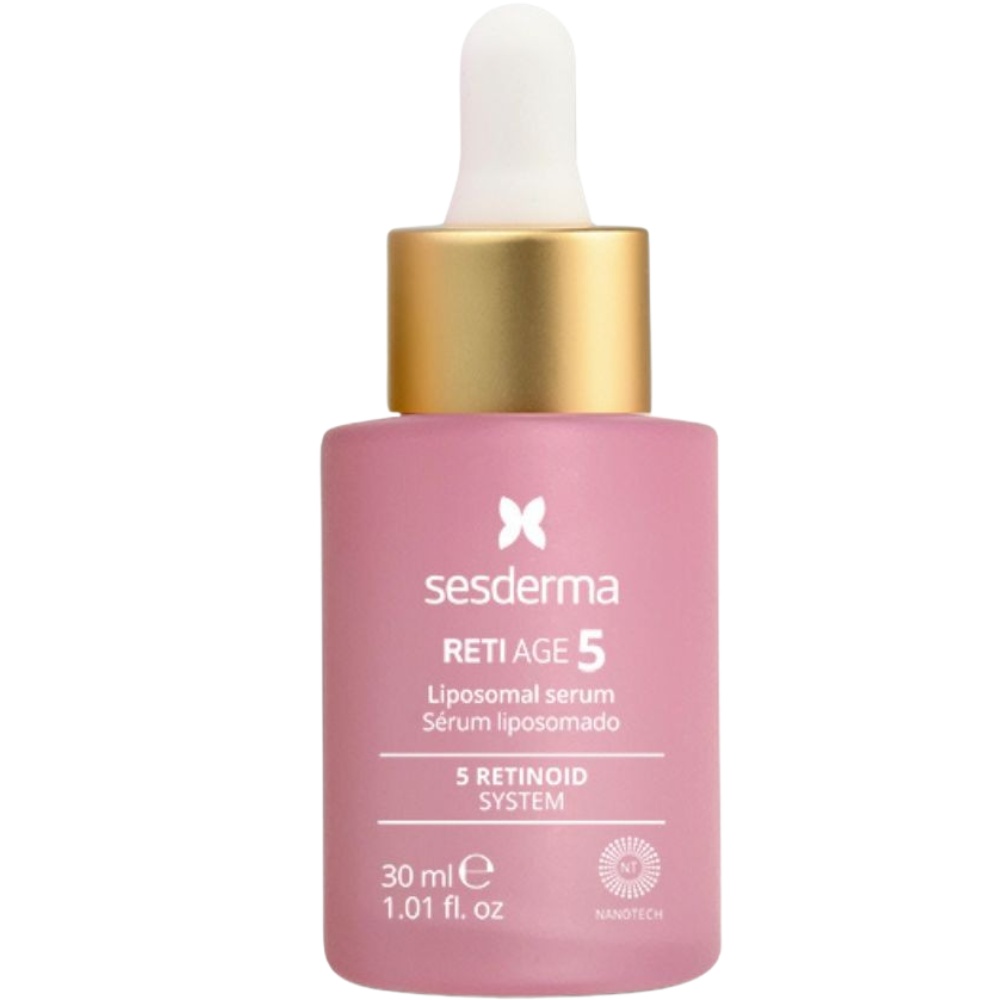
Sesderma Reti Age 5 Liposomal Serum Anti-Aging Innovation 30mLA facial serum for wrinkles and signs of ageing. Reduces wrinkles and fine lines. Hydrates and strengthens barrier. Restores youthful radiance. 5-Retinoid System: smooths wrinkles, accelerates renewal, and boosts collagen. Biomimetic Peptides: fill expression lines by stimulating collagen synthesis.54,51 £*Shipping: 5,34 £Secure redirect to the provider
-
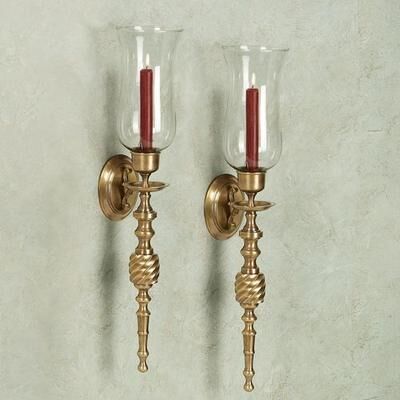
Flythe Consulting Brookville Wall Sconce Pair Antique Brass, Pair, Antique BrassThe Brookville Antique Brass Wall Sconce Pair uses simple design and a delicate aesthetic to create a truly elegant appeal. Each handcrafted, solid lacquered brass sconce has a scrolling arm, solid backplate, chain accents, and a 6 dia.x9 H etched...324,99 $*Shipping: 0,00 $Secure redirect to the provider
-
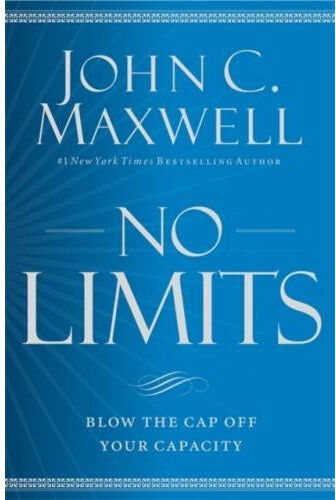
Little Brown Book Group No Limits: Blow the Cap Off Your Capacity by John C. Maxwell – Personal Growth & Leadership Development GuideNo Limits: Blow the CAP Off Your Capacity Description We often treat the word capacity as if it were a natural law of limitation. Unfortunately; most of us are much more comfortable defining what we perceive is off limits rather than what's possible. Could it be that many people have allowed what they perceive as capacity to define them? Have they allowed their perception to limit their attitudes about their potential? In his newest book; John Maxwell identifies 17 core capacities. Some of these are abilities we all already possess; such as energy; creativity and leadership. Others are aspects of our lives controlled by our choices; like our attitudes; character; and intentionality. Maxwell examines each of these 17 capacities; and provides clear and actionable advice on how you can increase your potential in each. He will guide you on how to identify; grow; and apply your critical capacities to your daily life. Once you've blown the 'cap' off your capacities; you'll find yourself more successful--and fulfilled--in your daily life.5,99 £*Shipping: 2,99 £Secure redirect to the provider

-
How does the mortgage work in Monopoly?
In Monopoly, players can purchase properties when they land on them. If a player lands on an unowned property and chooses not to buy it, the property goes up for auction. If a player cannot afford to purchase a property, they have the option to mortgage their own properties to raise funds. When a property is mortgaged, the owner receives cash equal to half of the property's value, but they must pay 10% interest when they unmortgage the property. **
-
Can the mortgage on the house increase?
Yes, the mortgage on a house can increase under certain circumstances. For example, if the homeowner has an adjustable-rate mortgage, the interest rate can increase over time, causing the monthly mortgage payment to go up. Additionally, if the homeowner has a mortgage with an escrow account for property taxes and homeowners insurance, an increase in these expenses can also lead to an increase in the monthly mortgage payment. Finally, if the homeowner takes out a home equity loan or line of credit, this can also increase the overall debt secured by the house. **
-
What do I need to cancel a mortgage?
To cancel a mortgage, you typically need to pay off the remaining balance of the loan. This can be done by making a lump sum payment for the full amount owed. Once the loan is paid off, the lender will provide you with a satisfaction of mortgage document, which officially cancels the mortgage lien on the property. It's important to follow the specific procedures outlined by your lender to ensure the mortgage is properly canceled. **
-
How can I tell if a mortgage still exists?
To determine if a mortgage still exists on a property, you can start by checking the public records at the county recorder's office where the property is located. Look for the deed of trust or mortgage document that was originally recorded when the loan was taken out. You can also contact the lender directly to inquire about the status of the mortgage and any outstanding balance. Additionally, you can request a copy of your credit report, which should list any current mortgages or liens on your property. **
How was the house purchased without a mortgage deed?
The house was purchased without a mortgage deed through a cash transaction. This means that the buyer paid for the house in full with their own funds, rather than taking out a mortgage loan from a bank or other financial institution. This type of transaction is common in situations where the buyer has enough savings or access to funds to purchase the property outright, without the need for a mortgage. **
How much does the assignment of a mortgage lien cost?
The cost of assigning a mortgage lien can vary depending on the specific circumstances and location. In general, the cost can range from a few hundred dollars to over a thousand dollars. This cost typically includes fees for preparing the assignment document, recording the assignment with the appropriate government office, and any other associated administrative costs. It is recommended to consult with a real estate attorney or a title company to get an accurate estimate of the cost for assigning a mortgage lien in a particular situation. **
Top-Angebote
Products related to Mortgage:
-
EISENBERG Anti-Ageing Expertise skin care setEISENBERG Anti-Ageing Expertise, , Skin Serums for Women, Everything for beautiful-looking skin in one package. The EISENBERG Anti-Ageing Expertise beauty gift set contains not one but several products to help you create or enrich your daily beauty routine and make you or your loved ones happy to get it as a gift. The set contains: Eisenberg Classique Soin Anti-Âge anti-wrinkle firming cream 50 ml Eisenberg Classique Hydra Lifting light gel-cream for intensive hydration 15 ml Eisenberg Classique Sérum Régénérant Liftant anti-wrinkle lifting serum for tired skin 7,5 ml Characteristics: a set of cosmetic products for everyday use products for deep nourishment and hydration for perfectly soft and smooth skin a treat for any woman How to use: Use every product from the cosmetic set according to the instructions.146,80 £*Shipping: 3,99 £Secure redirect to the provider
-
Flythe Consulting Arika Wall Sconce Pair, Pair, Satin NickelThe Arika Wall Sconce Pair is an adaptation of old-fashioned light fixtures, with an appealing design that will complement modern decor. The lacquered solid brass sconces have 4.75 dia.x7 H clear glass hurricanes that will protect your standard...179,00 $*Shipping: 22,95 $Secure redirect to the provider
-
Sesderma Reti Age 5 Liposomal Serum Anti-Aging Innovation 30mLA facial serum for wrinkles and signs of ageing. Reduces wrinkles and fine lines. Hydrates and strengthens barrier. Restores youthful radiance. 5-Retinoid System: smooths wrinkles, accelerates renewal, and boosts collagen. Biomimetic Peptides: fill expression lines by stimulating collagen synthesis.54,51 £*Shipping: 5,34 £Secure redirect to the provider
-
What is a primary mortgage financing?
A primary mortgage financing refers to the initial loan that a borrower obtains from a lender to purchase a home or property. This type of financing is typically used to cover the majority of the purchase price of the property, and is secured by the property itself. The borrower makes regular payments to the lender over a set period of time, usually 15 or 30 years, until the loan is fully repaid. Primary mortgage financing is a common way for individuals to become homeowners without having to pay the full purchase price upfront. **
-
Where can I get a mortgage deed?
You can obtain a mortgage deed from a mortgage lender or financial institution that is providing you with the loan for purchasing a property. The mortgage deed is a legal document that outlines the terms and conditions of the mortgage agreement between the borrower and the lender. It is typically prepared by the lender's legal team and signed by both parties before the loan is disbursed. **
-
How does the mortgage work in Monopoly?
In Monopoly, players can purchase properties when they land on them. If a player lands on an unowned property and chooses not to buy it, the property goes up for auction. If a player cannot afford to purchase a property, they have the option to mortgage their own properties to raise funds. When a property is mortgaged, the owner receives cash equal to half of the property's value, but they must pay 10% interest when they unmortgage the property. **
-
Can the mortgage on the house increase?
Yes, the mortgage on a house can increase under certain circumstances. For example, if the homeowner has an adjustable-rate mortgage, the interest rate can increase over time, causing the monthly mortgage payment to go up. Additionally, if the homeowner has a mortgage with an escrow account for property taxes and homeowners insurance, an increase in these expenses can also lead to an increase in the monthly mortgage payment. Finally, if the homeowner takes out a home equity loan or line of credit, this can also increase the overall debt secured by the house. **
Similar search terms for Mortgage
-
Flythe Consulting Brookville Wall Sconce Pair Antique Brass, Pair, Antique BrassThe Brookville Antique Brass Wall Sconce Pair uses simple design and a delicate aesthetic to create a truly elegant appeal. Each handcrafted, solid lacquered brass sconce has a scrolling arm, solid backplate, chain accents, and a 6 dia.x9 H etched...324,99 $*Shipping: 0,00 $Secure redirect to the provider
-
Little Brown Book Group No Limits: Blow the Cap Off Your Capacity by John C. Maxwell – Personal Growth & Leadership Development GuideNo Limits: Blow the CAP Off Your Capacity Description We often treat the word capacity as if it were a natural law of limitation. Unfortunately; most of us are much more comfortable defining what we perceive is off limits rather than what's possible. Could it be that many people have allowed what they perceive as capacity to define them? Have they allowed their perception to limit their attitudes about their potential? In his newest book; John Maxwell identifies 17 core capacities. Some of these are abilities we all already possess; such as energy; creativity and leadership. Others are aspects of our lives controlled by our choices; like our attitudes; character; and intentionality. Maxwell examines each of these 17 capacities; and provides clear and actionable advice on how you can increase your potential in each. He will guide you on how to identify; grow; and apply your critical capacities to your daily life. Once you've blown the 'cap' off your capacities; you'll find yourself more successful--and fulfilled--in your daily life.5,99 £*Shipping: 2,99 £Secure redirect to the provider
-
Officially Licensed Gas Safe Gas Safe® Warning Advisory Report Form - Pad of 50Our Gas Safe Premium Warning Advisory Record Pad features 50 sets of 3-part forms, now fully updated to comply with the latest Danger Do Not Use Warning Notice GSR-DDNUPAD1 regulations. These Licensed Gas Safe Premium Pads are thoughtfully designed in a landscape format, making it easier for engineers to complete records on-site. Each pad includes double covers with a writing guard, reinforced with triple stitching and binding tape for enhanced durability. The forms are individually numbered and perforated on the left-hand side, ensuring the spine remains intact when sections are removed. This pad is ideal for documenting unsafe gas appliance or installation faults, including Immediately Dangerous (ID), At Risk (AR), and Not to Current Standards (NCS) situations. Copies are provided for the gas user, the gas engineer/business, and, when necessary, the landlord.13,50 £*Shipping: 5,00 £Secure redirect to the provider
-
DK The Month-by-Month Baby Book: In-depth, Monthly Advice on Your Baby's Growth, Care, and Development in the First YearThe only book new parents will need for the extraordinary first year of their baby's life. This comprehensive book covers every moment of the first twelve months of your baby's life - from their first moments at home, feeding, and sleeping arrangements, to travelling, building their body strength, and starting to eat solids. A team of expert paediatricians, midwives, psychologists, and nutritionists provide unrivalled detail on everything new parents can expect. This new edition has been updated with the latest medical advice for a new generation of parents, and includes reassuring answers to common questions, offering additional support for whenever you need it. The Month-by-Month Baby Book perfectly complements the bestselling The Day-by-Day Pregnancy Book.16,99 £*Shipping: 2,99 £Secure redirect to the provider
-
What do I need to cancel a mortgage?
To cancel a mortgage, you typically need to pay off the remaining balance of the loan. This can be done by making a lump sum payment for the full amount owed. Once the loan is paid off, the lender will provide you with a satisfaction of mortgage document, which officially cancels the mortgage lien on the property. It's important to follow the specific procedures outlined by your lender to ensure the mortgage is properly canceled. **
-
How can I tell if a mortgage still exists?
To determine if a mortgage still exists on a property, you can start by checking the public records at the county recorder's office where the property is located. Look for the deed of trust or mortgage document that was originally recorded when the loan was taken out. You can also contact the lender directly to inquire about the status of the mortgage and any outstanding balance. Additionally, you can request a copy of your credit report, which should list any current mortgages or liens on your property. **
-
How was the house purchased without a mortgage deed?
The house was purchased without a mortgage deed through a cash transaction. This means that the buyer paid for the house in full with their own funds, rather than taking out a mortgage loan from a bank or other financial institution. This type of transaction is common in situations where the buyer has enough savings or access to funds to purchase the property outright, without the need for a mortgage. **
-
How much does the assignment of a mortgage lien cost?
The cost of assigning a mortgage lien can vary depending on the specific circumstances and location. In general, the cost can range from a few hundred dollars to over a thousand dollars. This cost typically includes fees for preparing the assignment document, recording the assignment with the appropriate government office, and any other associated administrative costs. It is recommended to consult with a real estate attorney or a title company to get an accurate estimate of the cost for assigning a mortgage lien in a particular situation. **
* All prices are inclusive of VAT and, if applicable, plus shipping costs. The offer information is based on the details provided by the respective shop and is updated through automated processes. Real-time updates do not occur, so deviations can occur in individual cases. ** Note: Parts of this content were created by AI.